Last Updated: September 2026
Car insurance rates can vary dramatically depending on where you live.
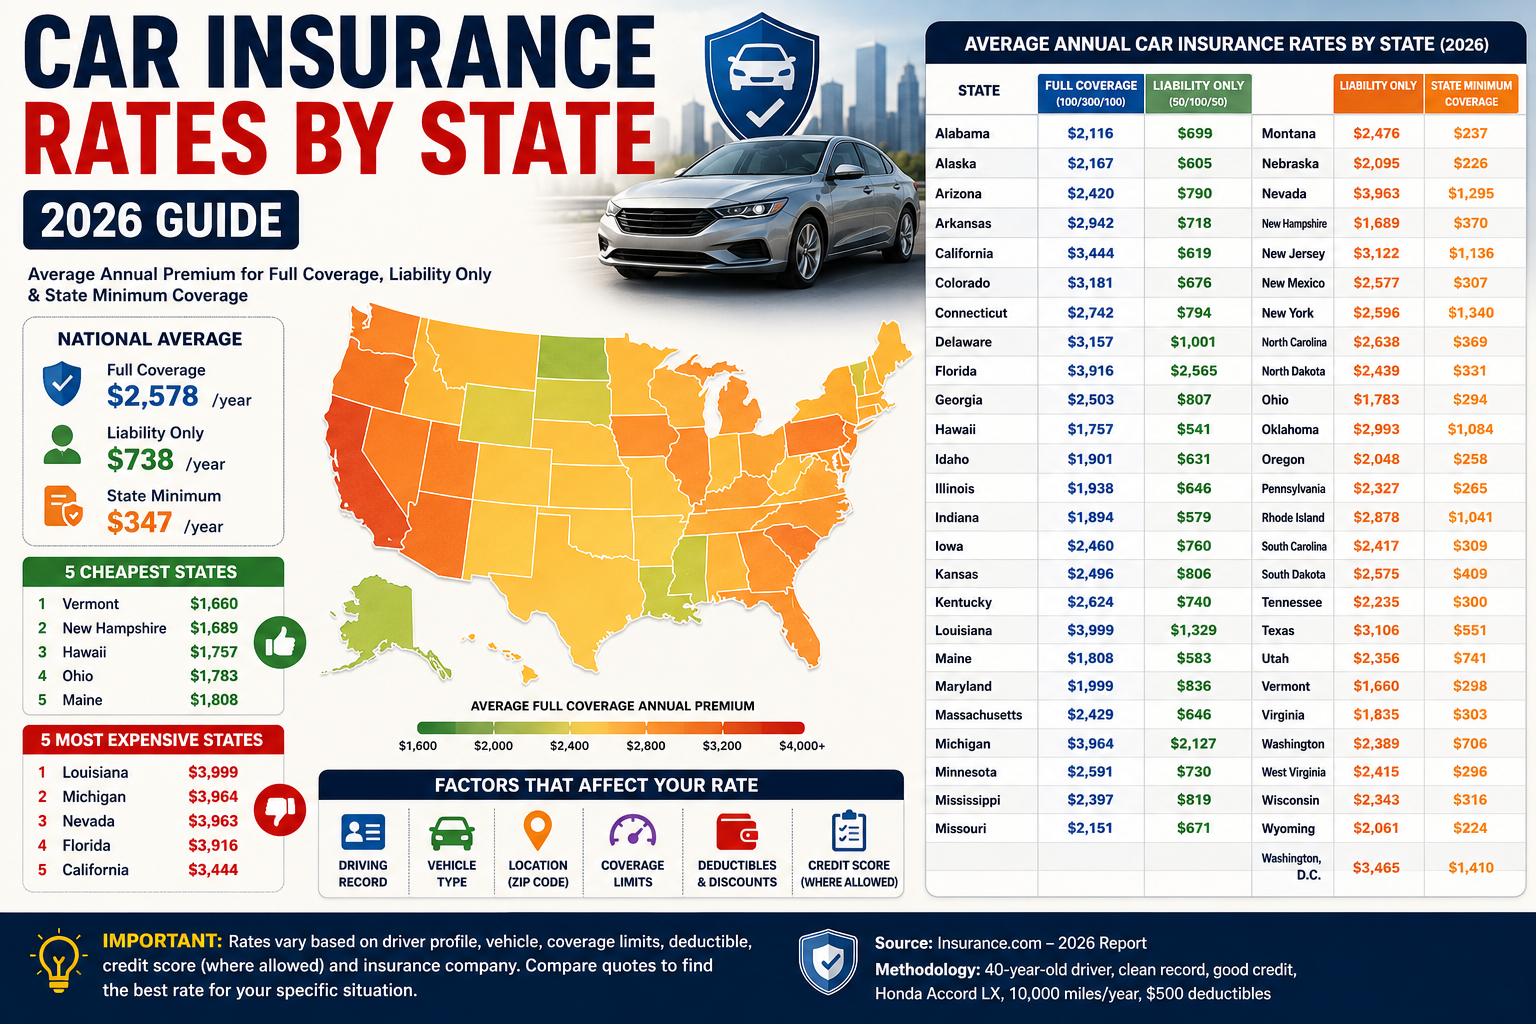
A driver in Vermont may pay substantially less for full coverage than a driver in Louisiana, even when their age, vehicle and driving history are similar. In 2026, Insurance.com data shows average full-coverage premiums ranging from about $1,660 per year in Vermont to $3,999 per year in Louisiana.
Your actual car insurance quote can be higher or lower than the state average. Insurers also consider factors such as your ZIP code, driving record, vehicle, age, mileage, coverage limits and, where permitted, credit-based insurance information.
This guide breaks down 2026 car insurance rates by state, including full coverage, liability-only and state-minimum coverage.
Average Car Insurance Rates by State in 2026
The table below shows average annual premiums for three common coverage levels.
| State | State Minimum | Liability Only | Full Coverage |
|---|---|---|---|
| Alabama | $1,? | $639 | $2,116 |
| Alaska | $588 | $605 | $2,167 |
| Arizona | — | — | $2,420 |
| Arkansas | — | — | $2,942 |
| California | — | — | $3,444 |
| Colorado | — | — | $3,181 |
| Connecticut | — | — | $2,742 |
| Delaware | — | — | $3,157 |
| Florida | — | — | $3,916 |
| Georgia | — | — | $2,503 |
| Hawaii | — | — | $1,757 |
| Idaho | — | — | $1,901 |
| Illinois | — | — | $1,938 |
| Indiana | — | — | $1,894 |
| Iowa | — | — | $2,460 |
| Kansas | — | — | $2,496 |
| Kentucky | — | — | $2,624 |
| Louisiana | — | — | $3,999 |
| Maine | — | — | $1,808 |
| Maryland | — | — | $1,999 |
| Massachusetts | — | — | $2,429 |
| Michigan | — | — | $3,964 |
| Minnesota | — | — | $2,591 |
| Mississippi | — | — | $2,397 |
| Missouri | — | — | $2,151 |
| Montana | — | — | $2,476 |
| Nebraska | — | — | $2,095 |
| Nevada | — | — | $3,963 |
| New Hampshire | — | — | $1,689 |
| New Jersey | — | — | $3,122 |
| New Mexico | — | — | $2,577 |
| New York | — | — | $2,596 |
| North Carolina | — | — | $2,638 |
| North Dakota | — | — | $2,439 |
| Ohio | — | — | $1,783 |
| Oklahoma | — | — | $2,993 |
| Oregon | — | — | $2,048 |
| Pennsylvania | — | — | $2,327 |
| Rhode Island | — | — | $2,878 |
| South Carolina | — | — | $2,417 |
| South Dakota | — | — | $2,575 |
| Tennessee | — | — | $2,235 |
| Texas | — | — | $3,106 |
| Utah | — | — | $2,356 |
| Vermont | — | — | $1,660 |
| Virginia | — | — | $1,835 |
| Washington | — | — | $2,389 |
| West Virginia | — | — | $2,415 |
| Wisconsin | — | — | $2,343 |
| Wyoming | — | — | $2,061 |
| Washington, D.C. | — | — | $3,465 |
Important: The complete state-level comparison below provides the exact 2026 figures for each coverage level. Insurance.com calculates its full-coverage averages using $100,000/$300,000 bodily injury liability, $100,000 property damage liability and $500 comprehensive/collision deductibles.
Full 2026 Car Insurance Rates by State
For a standardized comparison, Insurance.com’s 2026 full-coverage dataset assumes:
- 40-year-old driver
- Clean driving record
- Good credit
- Honda Accord LX
- 10,000 annual miles
- 12-mile commute
- $100,000/$300,000 bodily injury liability
- $100,000 property damage liability
- $500 comprehensive deductible
- $500 collision deductible
These assumptions matter because changing the driver, vehicle, coverage limits or deductible can produce a substantially different quote.
Alabama
- Full coverage: $2,116/year
- Monthly equivalent: about $176
- State minimum: varies based on required coverage
Alaska
- Full coverage: $2,167/year
- Monthly equivalent: about $181
- State minimum: $588/year
- Liability-only: $605/year
Arizona
- Full coverage: $2,420/year
- Monthly equivalent: about $202
Arkansas
- Full coverage: $2,942/year
- Monthly equivalent: about $245
California
- Full coverage: $3,444/year
- Monthly equivalent: about $287
Colorado
- Full coverage: $3,181/year
- Monthly equivalent: about $265
Connecticut
- Full coverage: $2,742/year
- Monthly equivalent: about $228
Delaware
- Full coverage: $3,157/year
- Monthly equivalent: about $263
Florida
- Full coverage: $3,916/year
- Monthly equivalent: about $326
Georgia
- Full coverage: $2,503/year
- Monthly equivalent: about $209
Hawaii
- Full coverage: $1,757/year
- Monthly equivalent: about $146
Idaho
- Full coverage: $1,901/year
- Monthly equivalent: about $158
Illinois
- Full coverage: $1,938/year
- Monthly equivalent: about $162
Indiana
- Full coverage: $1,894/year
- Monthly equivalent: about $158
Iowa
- Full coverage: $2,460/year
- Monthly equivalent: about $205
Kansas
- Full coverage: $2,496/year
- Monthly equivalent: about $208
Kentucky
- Full coverage: $2,624/year
- Monthly equivalent: about $219
Louisiana
- Full coverage: $3,999/year
- Monthly equivalent: about $333
Maine
- Full coverage: $1,808/year
- Monthly equivalent: about $151
Maryland
- Full coverage: $1,999/year
- Monthly equivalent: about $167
Massachusetts
- Full coverage: $2,429/year
- Monthly equivalent: about $202
Michigan
- Full coverage: $3,964/year
- Monthly equivalent: about $330
Minnesota
- Full coverage: $2,591/year
- Monthly equivalent: about $216
Mississippi
- Full coverage: $2,397/year
- Monthly equivalent: about $200
Missouri
- Full coverage: $2,151/year
- Monthly equivalent: about $179
Montana
- Full coverage: $2,476/year
- Monthly equivalent: about $206
Nebraska
- Full coverage: $2,095/year
- Monthly equivalent: about $175
Nevada
- Full coverage: $3,963/year
- Monthly equivalent: about $330
New Hampshire
- Full coverage: $1,689/year
- Monthly equivalent: about $141
New Jersey
- Full coverage: $3,122/year
- Monthly equivalent: about $260
New Mexico
- Full coverage: $2,577/year
- Monthly equivalent: about $215
New York
- Full coverage: $2,596/year
- Monthly equivalent: about $216
North Carolina
- Full coverage: $2,638/year
- Monthly equivalent: about $220
North Dakota
- Full coverage: $2,439/year
- Monthly equivalent: about $203
Ohio
- Full coverage: $1,783/year
- Monthly equivalent: about $149
Oklahoma
- Full coverage: $2,993/year
- Monthly equivalent: about $249
Oregon
- Full coverage: $2,048/year
- Monthly equivalent: about $171
Pennsylvania
- Full coverage: $2,327/year
- Monthly equivalent: about $194
Rhode Island
- Full coverage: $2,878/year
- Monthly equivalent: about $240
South Carolina
- Full coverage: $2,417/year
- Monthly equivalent: about $201
South Dakota
- Full coverage: $2,575/year
- Monthly equivalent: about $215
Tennessee
- Full coverage: $2,235/year
- Monthly equivalent: about $186
Texas
- Full coverage: $3,106/year
- Monthly equivalent: about $259
Utah
- Full coverage: $2,356/year
- Monthly equivalent: about $196
Vermont
- Full coverage: $1,660/year
- Monthly equivalent: about $138
Virginia
- Full coverage: $1,835/year
- Monthly equivalent: about $153
Washington
- Full coverage: $2,389/year
- Monthly equivalent: about $199
West Virginia
- Full coverage: $2,415/year
- Monthly equivalent: about $201
Wisconsin
- Full coverage: $2,343/year
- Monthly equivalent: about $195
Wyoming
- Full coverage: $2,061/year
- Monthly equivalent: about $172
Washington, D.C.
- Full coverage: $3,465/year
- Monthly equivalent: about $289
The state-by-state full-coverage figures above come from Insurance.com’s 2026 rate dataset.
The 5 Cheapest States for Car Insurance in 2026
According to Insurance.com’s 2026 data, these states have the lowest average full-coverage premiums:
| Rank | State | Average Annual Full Coverage |
|---|---|---|
| 1 | Vermont | $1,660 |
| 2 | New Hampshire | $1,689 |
| 3 | Hawaii | $1,757 |
| 4 | Ohio | $1,783 |
| 5 | Maine | $1,808 |
The national average is approximately $2,578 per year, so each of these states falls well below the national benchmark.
Why are rates lower in these states?
Lower population density, fewer accidents, lower theft rates and other local risk factors can contribute to lower insurance costs.
However, lower state averages don’t mean every driver in that state will receive a low quote.
The 5 Most Expensive States for Car Insurance in 2026
The highest average full-coverage rates in Insurance.com’s 2026 dataset are:
| Rank | State | Average Annual Full Coverage |
|---|---|---|
| 1 | Louisiana | $3,999 |
| 2 | Michigan | $3,964 |
| 3 | Nevada | $3,963 |
| 4 | Florida | $3,916 |
| 5 | California | $3,444 |
Louisiana’s average is about $1,421 above the national average.
Several factors can contribute to higher rates, including severe weather, accident frequency, uninsured drivers, repair costs, medical expenses, theft and insurance regulations.
Why Is Car Insurance More Expensive in Some States?
Insurance companies don’t charge everyone the same rate.
They evaluate the level of risk associated with different locations and driver profiles.
Some important factors include:
1. Accident Rates
Areas with more accidents can generate more insurance claims.
More claims can contribute to higher premiums.
2. Weather
Hurricanes, floods, hail, tornadoes, wildfires and other severe weather events can increase insurance losses.
States exposed to frequent severe weather can therefore have higher insurance costs.
3. Vehicle Theft
Higher theft rates can increase comprehensive insurance claims.
This can contribute to higher premiums in some cities and states.
4. Repair Costs
Modern vehicles contain expensive electronics, sensors and specialized components.
Higher repair costs can increase the amount insurers pay after accidents.
5. Medical Costs
In states where medical expenses associated with accidents are high, insurance claims can become more expensive.
6. Uninsured Drivers
When more drivers lack adequate insurance, insured drivers and insurers can face additional costs.
7. State Insurance Laws
Every state has its own insurance requirements and regulations.
Some states also use different approaches to auto insurance, which can affect premiums.
State Average vs. Your Actual Car Insurance Quote
One of the most important things to understand is that a state average isn’t a personalized quote.
For example, Insurance.com’s national full-coverage average is $2,578 per year.
That doesn’t mean every driver should expect to pay $2,578.
A 22-year-old driver with an accident and a high-performance vehicle could pay substantially more.
A 45-year-old driver with a clean record and an inexpensive vehicle could pay substantially less.
Your ZIP code can also make a difference.
Two drivers living in different neighborhoods within the same state can receive different rates.
What Factors Affect Your Car Insurance Rate?
Age
Young drivers generally pay higher premiums because they have less driving experience.
Rates can change as drivers gain experience and move into different age groups.
Driving Record
Tickets, accidents and serious violations can increase your premium.
A clean record may help you qualify for better rates or discounts.
Vehicle
The car you drive can have a significant impact.
Insurers may consider:
- Vehicle value
- Repair costs
- Safety features
- Theft risk
- Claims history
- Replacement parts
- Performance
Credit-Based Insurance Information
Where permitted, insurers may use credit-based insurance information as one factor in determining rates.
State rules differ, so this practice isn’t identical everywhere.
Mileage
Drivers who travel fewer miles may qualify for lower rates or low-mileage programs with certain insurers.
Coverage Limits
Higher coverage limits generally provide greater protection but can increase your premium.
Deductible
A higher deductible can reduce your premium for applicable coverage, but it also means you’ll pay more out of pocket after a covered claim.
Full Coverage vs. Liability-Only Insurance
Another reason car insurance rates differ is the amount of coverage you purchase.
Liability-only insurance
Liability insurance generally helps cover certain injuries or property damage you cause to others, subject to your policy limits.
It typically doesn’t pay to repair your own vehicle after an accident you caused.
Full coverage
“Full coverage” isn’t a specific policy type defined identically in every state.
The term generally refers to a policy that combines liability insurance with comprehensive and collision coverage.
Collision coverage can help pay for covered damage to your vehicle after a collision.
Comprehensive coverage can help cover certain non-collision losses, such as theft or damage from certain weather events.
Your policy may also include other required or optional coverage depending on your state.
How to Find Cheap Car Insurance in Your State
Finding a low rate doesn’t necessarily require sacrificing coverage.
Try these steps.
1. Compare Multiple Insurance Companies
Get quotes from several insurers.
Different companies can price the same driver very differently.
2. Compare Identical Coverage
When comparing quotes, use the same:
- Liability limits
- Deductibles
- Comprehensive coverage
- Collision coverage
- Optional coverage
Otherwise, you aren’t making a true price comparison.
3. Ask About Discounts
Ask insurers whether you qualify for:
- Safe-driver discounts
- Multi-policy discounts
- Multi-car discounts
- Good-student discounts
- Defensive-driving discounts
- Low-mileage discounts
- Vehicle-safety discounts
Discount availability varies.
4. Review Your Deductible
Ask how your premium changes if you increase your deductible.
Only choose a deductible you can comfortably afford.
5. Check Your Coverage
Your insurance needs may change over time.
Review your policy when:
- You move
- You buy a new vehicle
- You pay off your vehicle
- Your mileage changes
- A driver joins or leaves your household
- Your financial circumstances change
How Much Is Car Insurance Per Month by State?
For full coverage, monthly equivalents range from approximately:
- $138/month in Vermont
- $141/month in New Hampshire
- $146/month in Hawaii
- $149/month in Ohio
- $151/month in Maine
At the expensive end:
- $333/month in Louisiana
- $330/month in Michigan
- $330/month in Nevada
- $326/month in Florida
- $287/month in California
These monthly figures are annual premiums divided by 12 and are useful for budgeting. Actual billing amounts can differ depending on payment schedules, fees and insurer practices.
Which State Has the Cheapest Car Insurance?
Based on Insurance.com’s 2026 full-coverage data, Vermont has the lowest average annual premium at $1,660.
New Hampshire, Hawaii, Ohio and Maine are also among the least expensive states.
However, another insurer’s dataset may produce a different ranking because insurance companies and research organizations use different methodologies and driver assumptions.
Which State Has the Most Expensive Car Insurance?
According to Insurance.com’s 2026 data, Louisiana has the highest average full-coverage premium at $3,999 per year.
Michigan and Nevada follow closely behind at $3,964 and $3,963 respectively.
Drivers in these states should still compare multiple companies because individual rates can differ substantially from the state average.
Why Your ZIP Code Matters
Your state is only part of the picture.
Insurance companies can also consider your specific location.
A ZIP code with:
- Heavy traffic
- More accidents
- Higher theft rates
- More claims
- Higher repair costs
- Higher population density
may have different rates from another ZIP code in the same state.
That’s why using only a state average to determine whether your insurance is expensive can be misleading.
How to Tell If You’re Paying Too Much
There isn’t a single premium that automatically means you’re overpaying.
Instead, compare your current policy with several competing quotes.
Make sure the comparison uses:
The same vehicle + same drivers + same coverage + same deductibles.
For example, if your current policy costs $220 per month but includes much higher liability limits than another $160 quote, the lower quote isn’t necessarily the better deal.
Compare protection first, then price.
Frequently Asked Questions
What state has the cheapest car insurance in 2026?
Vermont has the lowest average full-coverage premium in Insurance.com’s 2026 dataset, at approximately $1,660 per year.
What state has the most expensive car insurance in 2026?
Louisiana has the highest average full-coverage premium in Insurance.com’s 2026 dataset, at approximately $3,999 per year.
What is the average cost of car insurance in the U.S. in 2026?
Insurance.com’s 2026 national average is approximately $2,578 per year, or $215 per month, for full coverage using its standardized coverage assumptions.
Why is car insurance so expensive in my state?
Insurance costs can be influenced by accidents, weather, theft, repair costs, medical expenses, uninsured drivers, state regulations and other risk factors.
Does moving to another state change car insurance?
It can. Insurers price policies based partly on location, and every state has different insurance requirements and risk characteristics.
Does my ZIP code affect car insurance?
Yes. Insurers can use location-related risk factors when determining premiums, so rates can vary within the same state.
Is full coverage worth it?
It depends on your vehicle’s value, finances, lender requirements and risk tolerance. Drivers with financed or leased vehicles may have specific coverage requirements.
How can I get cheaper car insurance?
Compare multiple insurers, ask about discounts, review your coverage, consider an appropriate deductible and maintain a clean driving record.
Are state averages actual insurance quotes?
No. State averages are benchmarks. Your personalized quote can be significantly different depending on your driver profile, vehicle, location and coverage.
Final Takeaway
Car insurance prices vary dramatically across the United States in 2026.
The national average for full coverage is approximately $2,578 per year, but Insurance.com’s state averages range from $1,660 in Vermont to $3,999 in Louisiana.
Your actual premium depends on much more than your state.
Your ZIP code, age, driving record, vehicle, mileage, coverage limits, deductible and other rating factors can all influence what you pay.
If your premium seems high, don’t assume you’re stuck with it.
Compare several insurers using the same coverage levels, ask about available discounts and review your policy before renewal.
The best rate isn’t simply the lowest number—it’s the lowest price for the coverage you actually need.