Last Updated: September 2026
Buying life insurance sounds simple until you have to answer one important question:
How much life insurance do I actually need?
You may have heard that you should buy 10 times your annual income. While that can be a useful starting point, it isn’t a complete calculation.
Your ideal coverage amount depends on your income, debts, mortgage, children, savings, future goals and the people who depend on you financially.
For example, someone earning $75,000 a year with two children and a mortgage may need significantly more coverage than another person earning the same salary with no dependents or major debts.
The National Association of Insurance Commissioners (NAIC) recommends considering factors such as how much family income you provide, who depends on you financially, debts, final expenses, education costs and future financial needs when determining coverage.
So rather than choosing an arbitrary number, it’s better to estimate what your family would actually need if your income disappeared.
How Much Life Insurance Do You Need?
There is no universal coverage amount that works for everyone.
A quick rule of thumb is:
Annual income × 10 = basic life insurance estimate
For example:
- $50,000 income → about $500,000 coverage
- $75,000 income → about $750,000 coverage
- $100,000 income → about $1 million coverage
- $150,000 income → about $1.5 million coverage
However, this method doesn’t account for your mortgage, debts, savings, children’s education or other financial obligations.
NerdWallet’s 2026 guidance describes the 10-times-income approach as a useful starting point but recommends a more detailed calculation for a more accurate estimate.
For many families, the better approach is to calculate what needs to be paid, how much income needs to be replaced and what existing assets can offset those needs.
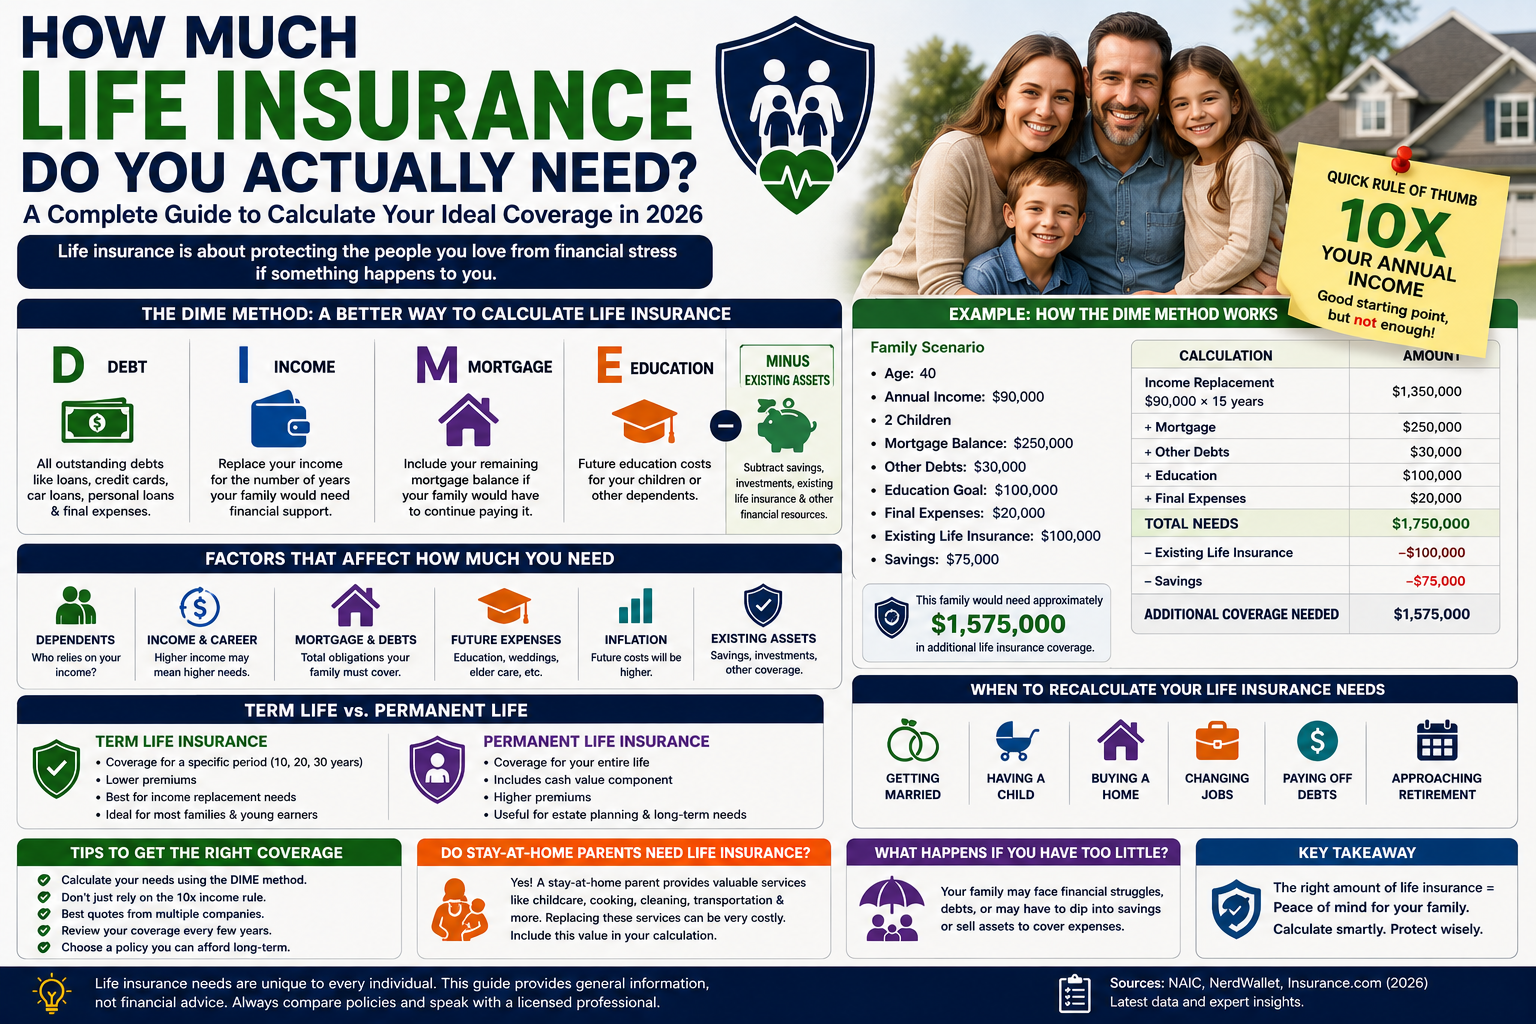
The DIME Method: A Better Way to Calculate Life Insurance
One of the most useful methods for estimating life insurance coverage is the DIME formula.
DIME stands for:
- D — Debt
- I — Income
- M — Mortgage
- E — Education
The method adds these major financial obligations together and then accounts for existing resources such as savings and current life insurance.
According to NerdWallet’s 2026 life insurance guidance, the DIME approach provides a more detailed estimate than simply multiplying income by a fixed number.
Let’s break it down.
D — Debt and Final Expenses
Start by listing debts your family may have to deal with after your death.
This could include:
- Credit card balances
- Personal loans
- Auto loans
- Private student loans
- Other outstanding debts
- Funeral and final expenses
Don’t automatically include every debt.
For example, some debts may be discharged or handled differently depending on the type of debt and the circumstances.
The goal is to identify financial obligations that could create a burden for the people you leave behind.
I — Income Replacement
Next, estimate how much of your income your family would need to replace.
Ask yourself:
How many years would my family need financial support if I died today?
For example, suppose you earn:
$80,000 per year
and you want to replace that income for 15 years.
Your initial income-replacement calculation would be:
$80,000 × 15 = $1.2 million
This doesn’t necessarily mean you need a $1.2 million policy because you may have savings, existing insurance and other financial resources.
It simply gives you a starting point.
NerdWallet notes that income replacement should consider the number of years dependents would need support and that additional future expenses may need to be included.
M — Mortgage
If you have a mortgage, consider whether you want your life insurance benefit to pay it off.
Suppose your remaining mortgage balance is:
$300,000
You may want your life insurance calculation to include enough coverage to eliminate that obligation.
That could allow your family to remain in the home without having to continue making mortgage payments.
However, paying off the mortgage isn’t the only possible strategy.
Some families may prefer to keep the mortgage and use the insurance proceeds for income replacement or other financial needs.
The important thing is to include the mortgage in your calculation if it would create a meaningful financial burden for your survivors.
E — Education
If you have children, consider future education costs.
You don’t necessarily need to predict the exact cost decades into the future.
Instead, estimate how much you would like to provide for:
- College tuition
- Vocational education
- Private schooling
- Other education expenses
For example, if you want to reserve $100,000 for your children’s future education, that amount can be included in your coverage calculation.
NerdWallet’s DIME guidance specifically includes education expenses as one component of determining life insurance needs.
Don’t Forget Your Existing Assets
Once you’ve calculated your financial needs, consider what resources your family already has.
These may include:
- Savings
- Existing life insurance
- Certain liquid investments
- Employer-provided life insurance
- Other financial assets
For example:
Estimated financial needs
Income replacement: $1,000,000
Mortgage: $250,000
Other debts: $50,000
Education: $100,000
Final expenses: $20,000
Total: $1,420,000
Now suppose you already have:
Existing life insurance: $250,000
Savings available for this purpose: $70,000
Total existing resources: $320,000
Your estimated additional need would be:
$1,420,000 − $320,000 = $1.1 million
This is an illustration, not a recommendation for a specific person.
Your calculation may be very different.
Example: How Much Life Insurance Does a Family Need?
Let’s consider a hypothetical family.
Example household
Age: 40
Annual income: $90,000
Children: 2
Mortgage balance: $250,000
Other debts: $30,000
Education goal: $100,000
Savings: $75,000
Existing life insurance: $100,000
Suppose the family wants to replace 15 years of income.
Step 1: Income replacement
$90,000 × 15 = $1,350,000
Step 2: Add mortgage
$1,350,000 + $250,000 = $1,600,000
Step 3: Add other debts
$1,600,000 + $30,000 = $1,630,000
Step 4: Add education
$1,630,000 + $100,000 = $1,730,000
Step 5: Add final expenses
Assume $20,000:
$1,730,000 + $20,000 = $1,750,000
Step 6: Subtract existing resources
Existing insurance: $100,000
Savings: $75,000
$1,750,000 − $175,000 = $1,575,000
The family’s rough additional coverage need would therefore be around:
$1.575 million
Again, this is simply an example showing how the calculation works.
A real coverage decision should account for taxes, investment returns, inflation, future income changes, existing benefits and other circumstances.
Do Stay-at-Home Parents Need Life Insurance?
Yes, potentially.
A common mistake is to assume that only the person earning a salary needs life insurance.
But a stay-at-home parent can provide substantial economic value through:
- Childcare
- Household management
- Transportation
- Meal preparation
- Home responsibilities
- Education and supervision
- Other unpaid work
If that person dies, the surviving parent may suddenly need to pay for services that were previously provided within the household.
The NAIC specifically recommends considering the value of services provided by people who depend on the family financially, rather than looking only at salary.
For example, if replacing childcare and household responsibilities would cost tens of thousands of dollars per year, that potential expense should be considered when estimating coverage.
How Much Life Insurance Should a Single Person Have?
Not everyone needs a large life insurance policy.
If nobody depends on your income and you don’t have major financial obligations that would transfer to others, your need may be relatively small.
However, you might still consider coverage if you have:
- A mortgage with a co-borrower
- Co-signed debt
- Private student loans
- Dependents
- Business obligations
- Significant final expenses
- Someone you financially support
Your situation matters more than a simple age or income rule.
How Much Life Insurance Should Parents Have?
Parents often need more coverage because multiple people may depend on their income.
When calculating coverage, consider:
Income replacement
How long would your children and spouse need financial support?
Childcare
Would the surviving parent need to pay for additional childcare?
Education
How much would you like to contribute toward your children’s education?
Housing
Would your family be able to afford the mortgage and other housing expenses?
Daily expenses
Food, utilities, transportation and other recurring expenses don’t disappear after a parent’s death.
Existing benefits
Include employer life insurance and other resources when estimating the remaining gap.
Should You Buy 10 Times Your Income?
The 10× income rule can be useful as a quick estimate.
But it shouldn’t automatically determine your policy size.
Consider someone earning $100,000 annually.
The 10× rule suggests:
$1 million
But suppose that person also has:
- $400,000 mortgage
- Two children
- $50,000 education savings goal
- $40,000 other debt
- $25,000 final expenses
A $1 million policy may or may not be enough depending on existing savings, other insurance and the number of years of income replacement required.
That’s why detailed calculations are usually more useful.
How Long Should Your Life Insurance Policy Last?
The amount of coverage isn’t the only decision.
You also need to decide how long you need the coverage.
A common approach is to choose a term that lasts through your major financial responsibilities.
For example, you might consider coverage until:
- Your children become financially independent
- Your mortgage is substantially paid off
- You reach retirement
- Your spouse reaches retirement age
- Major debts are paid
- Your financial assets become sufficient to support your family
The right term depends on your circumstances.
Term Life vs. Permanent Life Insurance
There are two broad categories of life insurance:
Term Life Insurance
Term life insurance provides coverage for a specific period.
For example:
- 10 years
- 20 years
- 30 years
It generally has lower initial premiums than permanent life insurance.
If you die while the policy is active, your beneficiaries generally receive the death benefit, subject to the policy terms.
If you outlive the term, the policy typically doesn’t pay a death benefit unless specific policy features apply.
Permanent Life Insurance
Permanent insurance is designed to provide coverage for a much longer period, potentially for your entire life.
Examples include:
- Whole life
- Universal life
- Variable life
These policies can include a cash-value component, depending on the policy.
Because of their additional features and longer coverage period, permanent policies are generally more expensive than term insurance.
The NAIC identifies term and cash-value policies as the two basic categories of life insurance and notes that permanent policies generally have higher premiums because of their savings/cash-value component.
How Much Life Insurance Can You Afford?
Your coverage needs matter, but your budget matters too.
Don’t choose a policy so expensive that you are likely to stop paying premiums.
A smaller policy that stays in force can be more useful than a much larger policy that becomes unaffordable.
When comparing policies, look at:
- Monthly premium
- Coverage amount
- Policy term
- Renewal provisions
- Conversion options
- Riders
- Exclusions
- Premium guarantees
- Financial strength of the insurer
Is Employer Life Insurance Enough?
Employer-provided life insurance can be useful, but it may not be enough for your family’s total needs.
Some workplace plans provide coverage based on a multiple of salary.
For example, if your employer provides one year’s salary in life insurance and you earn $80,000, your employer coverage could be $80,000.
That may be significantly less than what your family actually needs.
NerdWallet notes that workplace group life insurance may commonly be limited to one or two times salary and may not be sufficient for a household’s complete financial needs.
Another consideration is portability.
Some employer policies may not remain with you if you leave your job.
Check your specific employee benefits documents to understand the rules.
When Should You Recalculate Your Life Insurance Needs?
Your coverage shouldn’t necessarily stay unchanged forever.
Revisit your calculation after major life events.
These can include:
Getting married
Your spouse may become financially dependent on your income.
Having a child
Children can dramatically increase the amount and duration of financial support required.
Buying a home
A mortgage can create a major long-term obligation.
Changing jobs
Your income and employer-provided benefits may change.
Getting divorced
Your financial responsibilities and beneficiaries may change.
Paying off major debts
Your required coverage could decrease.
Receiving a large inheritance
Your existing financial resources may increase.
Starting a business
Business debts or obligations may create additional coverage needs.
NerdWallet recommends reassessing life insurance needs after major financial milestones because those changes can significantly affect coverage requirements.
What Happens If You Have Too Little Life Insurance?
Underinsurance can leave your family with a financial gap.
For example, imagine your family needs $1.5 million but your policy only provides $500,000.
The remaining $1 million may need to come from:
- Savings
- Investments
- Future income
- Asset sales
- Government benefits
- Other financial resources
That doesn’t automatically mean you need a $1.5 million policy.
It means you should understand the gap between your family’s potential needs and the resources available to them.
What Happens If You Have Too Much Life Insurance?
More coverage isn’t automatically better.
A policy that provides substantially more coverage than your family needs may result in unnecessary premiums.
That’s why the goal isn’t to buy the biggest policy you can qualify for.
The goal is to buy appropriate coverage for the financial risk you’re trying to protect against.
A Simple Life Insurance Calculator
You can use this basic formula to create a starting estimate:
Step 1
Calculate income replacement:
Annual income × number of years
Step 2
Add:
Mortgage balance
Step 3
Add:
Other debts
Step 4
Add:
Education expenses
Step 5
Add:
Final expenses
Step 6
Subtract:
Existing life insurance
Step 7
Subtract:
Relevant savings and other assets
Basic Formula
Life Insurance Need = Income Replacement + Mortgage + Debts + Education + Final Expenses − Existing Resources
This isn’t a perfect financial model, but it can provide a much better starting point than simply guessing.
Life Insurance Coverage Examples
Here are some simplified examples:
| Situation | Possible Starting Point |
|---|---|
| Single person, no dependents | May need little or no income-replacement coverage |
| Single person with co-signed debt | Consider debt and final expenses |
| Married, no children | Consider income replacement and mortgage |
| Parent with young children | Consider income, childcare, education and mortgage |
| Stay-at-home parent | Consider childcare and household services |
| High-income household | Consider larger income-replacement need |
| Business owner | Consider personal and business obligations |
| Near retirement | Reassess whether income replacement is still necessary |
These are general examples, not personalized recommendations.
Frequently Asked Questions
Is 10 times my salary enough for life insurance?
It can be a useful starting point, but it isn’t necessarily enough.
A detailed calculation should also consider debts, mortgage, education expenses, savings, existing insurance and the number of years your family needs income replacement.
Is $500,000 enough life insurance?
It depends.
For someone with no dependents and few financial obligations, $500,000 could be substantial.
For a household with a large mortgage, young children and significant income-replacement needs, it may not be enough.
How much life insurance does a 30-year-old need?
Age alone doesn’t determine the answer.
A 30-year-old parent with a mortgage may have a much greater need than a 30-year-old single person without dependents.
Calculate your financial obligations rather than choosing coverage based solely on age.
How much life insurance does a 40-year-old need?
The same principle applies.
Income, dependents, debts, mortgage, savings and future financial goals are more important than age alone.
Does a stay-at-home spouse need life insurance?
Potentially, yes.
Even without a salary, a stay-at-home spouse may provide valuable childcare and household services that would become expensive to replace.
Should I include my mortgage when calculating life insurance?
If your family would face the mortgage after your death, it can make sense to include the outstanding balance in your coverage calculation.
Should I subtract my savings?
Potentially, but be conservative.
Only count assets that would realistically be available to support your beneficiaries and don’t assume every asset can immediately replace lost income.
Should I count employer-provided life insurance?
Yes.
If your employer provides life insurance, include the coverage when calculating your overall insurance gap.
But also check whether the coverage remains available if you leave the job.
Should I buy term or whole life insurance?
For many people primarily seeking income replacement for a defined period, term life insurance can be a straightforward option.
Permanent insurance may make sense for specific long-term financial or estate-planning goals.
The appropriate choice depends on your needs, budget and financial situation.
Final Takeaway
So, how much life insurance do you actually need?
There isn’t one number that works for everyone.
The common 10× income rule can give you a quick starting point, but a more useful approach is to calculate your actual financial obligations.
Start with:
Income replacement + mortgage + debts + education + final expenses
Then subtract:
Existing life insurance + relevant financial resources
Also think about the people who depend on you, including the economic value of a stay-at-home spouse or parent.
The most important goal isn’t buying the largest possible policy.
It’s making sure the people who depend on you would have enough financial support to handle the loss of your income and other financial responsibilities.
Life insurance needs can change as your family, income, debts and assets change, so it’s worth reviewing your coverage after major life events.
Important: This article provides general educational information and is not personalized financial or insurance advice. Insurance needs vary by individual circumstances. Before purchasing a policy, compare coverage, policy terms, exclusions and premiums and consider speaking with a qualified insurance or financial professional.
SEO Package
SEO Title: How Much Life Insurance Do You Need in 2026? Complete Guide
Meta Description: How much life insurance do you actually need? Learn how to calculate coverage using income, debts, mortgage, education costs, savings and the DIME method.
Suggested URL:zuni2i.fun/how-much-life-insurance-do-you-need/
Primary Keyword:how much life insurance do I need
Secondary Keywords:
- how much life insurance do you need
- how much life insurance should I have
- life insurance calculator
- life insurance coverage calculator
- how to calculate life insurance needs
- how much life insurance do I need in 2026
- DIME life insurance formula
- 10 times income life insurance rule
- life insurance for families
- how much term life insurance do I need
Featured Image Text:
HOW MUCH LIFE INSURANCE DO YOU ACTUALLY NEED?
Suggested Internal Links:
- How Much Should Car Insurance Cost in 2026?
- Best Car Insurance Companies in 2026
- How to Lower Your Car Insurance Premium
- Car Insurance Rates by State: 2026 Guide
- How Much Does Homeowners Insurance Cost in 2026?
- Best Homeowners Insurance Companies in 2026
- How Much Does Life Insurance Cost in 2026?
- How Much Does Health Insurance Cost in 2026?
- Best Insurance Companies in 2026: Compare Your Options